Federal Deposit Insurance: Core Concepts, Relevance, and Applications
=====================================================================
**Introduction**
One of the key aspects of financial crisis management is ensuring the stability of the banking sector, which holds the life savings of millions of people and businesses. During financial crises, such as the one that occurred in 2008, banks may find themselves in a precarious position where depositors fear losing their savings, leading to massive withdrawals and bank failures. To prevent this vicious cycle and maintain the public's trust in the banking system, the Federal Deposit Insurance Corporation (FDIC) was created to offer federal deposit insurance to depositors.
[](https://upload.wikimedia.org/wikipedia/commons/thumb/e/e6/US-FDIC-Logo.svg/1200px-US-FDIC-Logo.svg.png)
*The logo of the Federal Deposit Insurance Corporation \(FDIC\).*
_Federal deposit insurance_ is an insurance program designed to protect the depositors of a failed bank from the loss of their deposits. In the United States, the FDIC, as an independent agency of the federal government, has the authority to insure bank deposits, regulate and supervise banks, and resolve failed banks. The FDIC provides insurance coverage for up to $250,000 per depositor, per insured bank, for each account ownership category. Deposit insurance eliminates the need for individual depositors to evaluate the safety and soundness of each bank, promoting public trust in the banking sector and ensuring the orderly resolution of failed banks.
**Relevance of Federal Deposit Insurance**
1. **Mitigating Systemic Risk**: Federal deposit insurance protects a vast number of depositors and promotes financial stability. It offers a safety net for the general population and reduces the systemic risk associated with bank failures. In the words of Ben S. Bernanke (Bernanke, Geithner, and Paulson, 2019, p. 318) "Deposit insurance plays a vital role in containing shocks to the financial system and the economy."
2. **Maintaining Public Trust**: Federal deposit insurance, by protecting the funds of individual depositors, preserves public trust in the banking sector. As argued by Timothy F. Geithner (Bernanke, Geithner, and Paulson, 2019, p. 320), "The most immediate benefit of deposit insurance is that it helps to preserve the trust of depositors in a financial institution."
[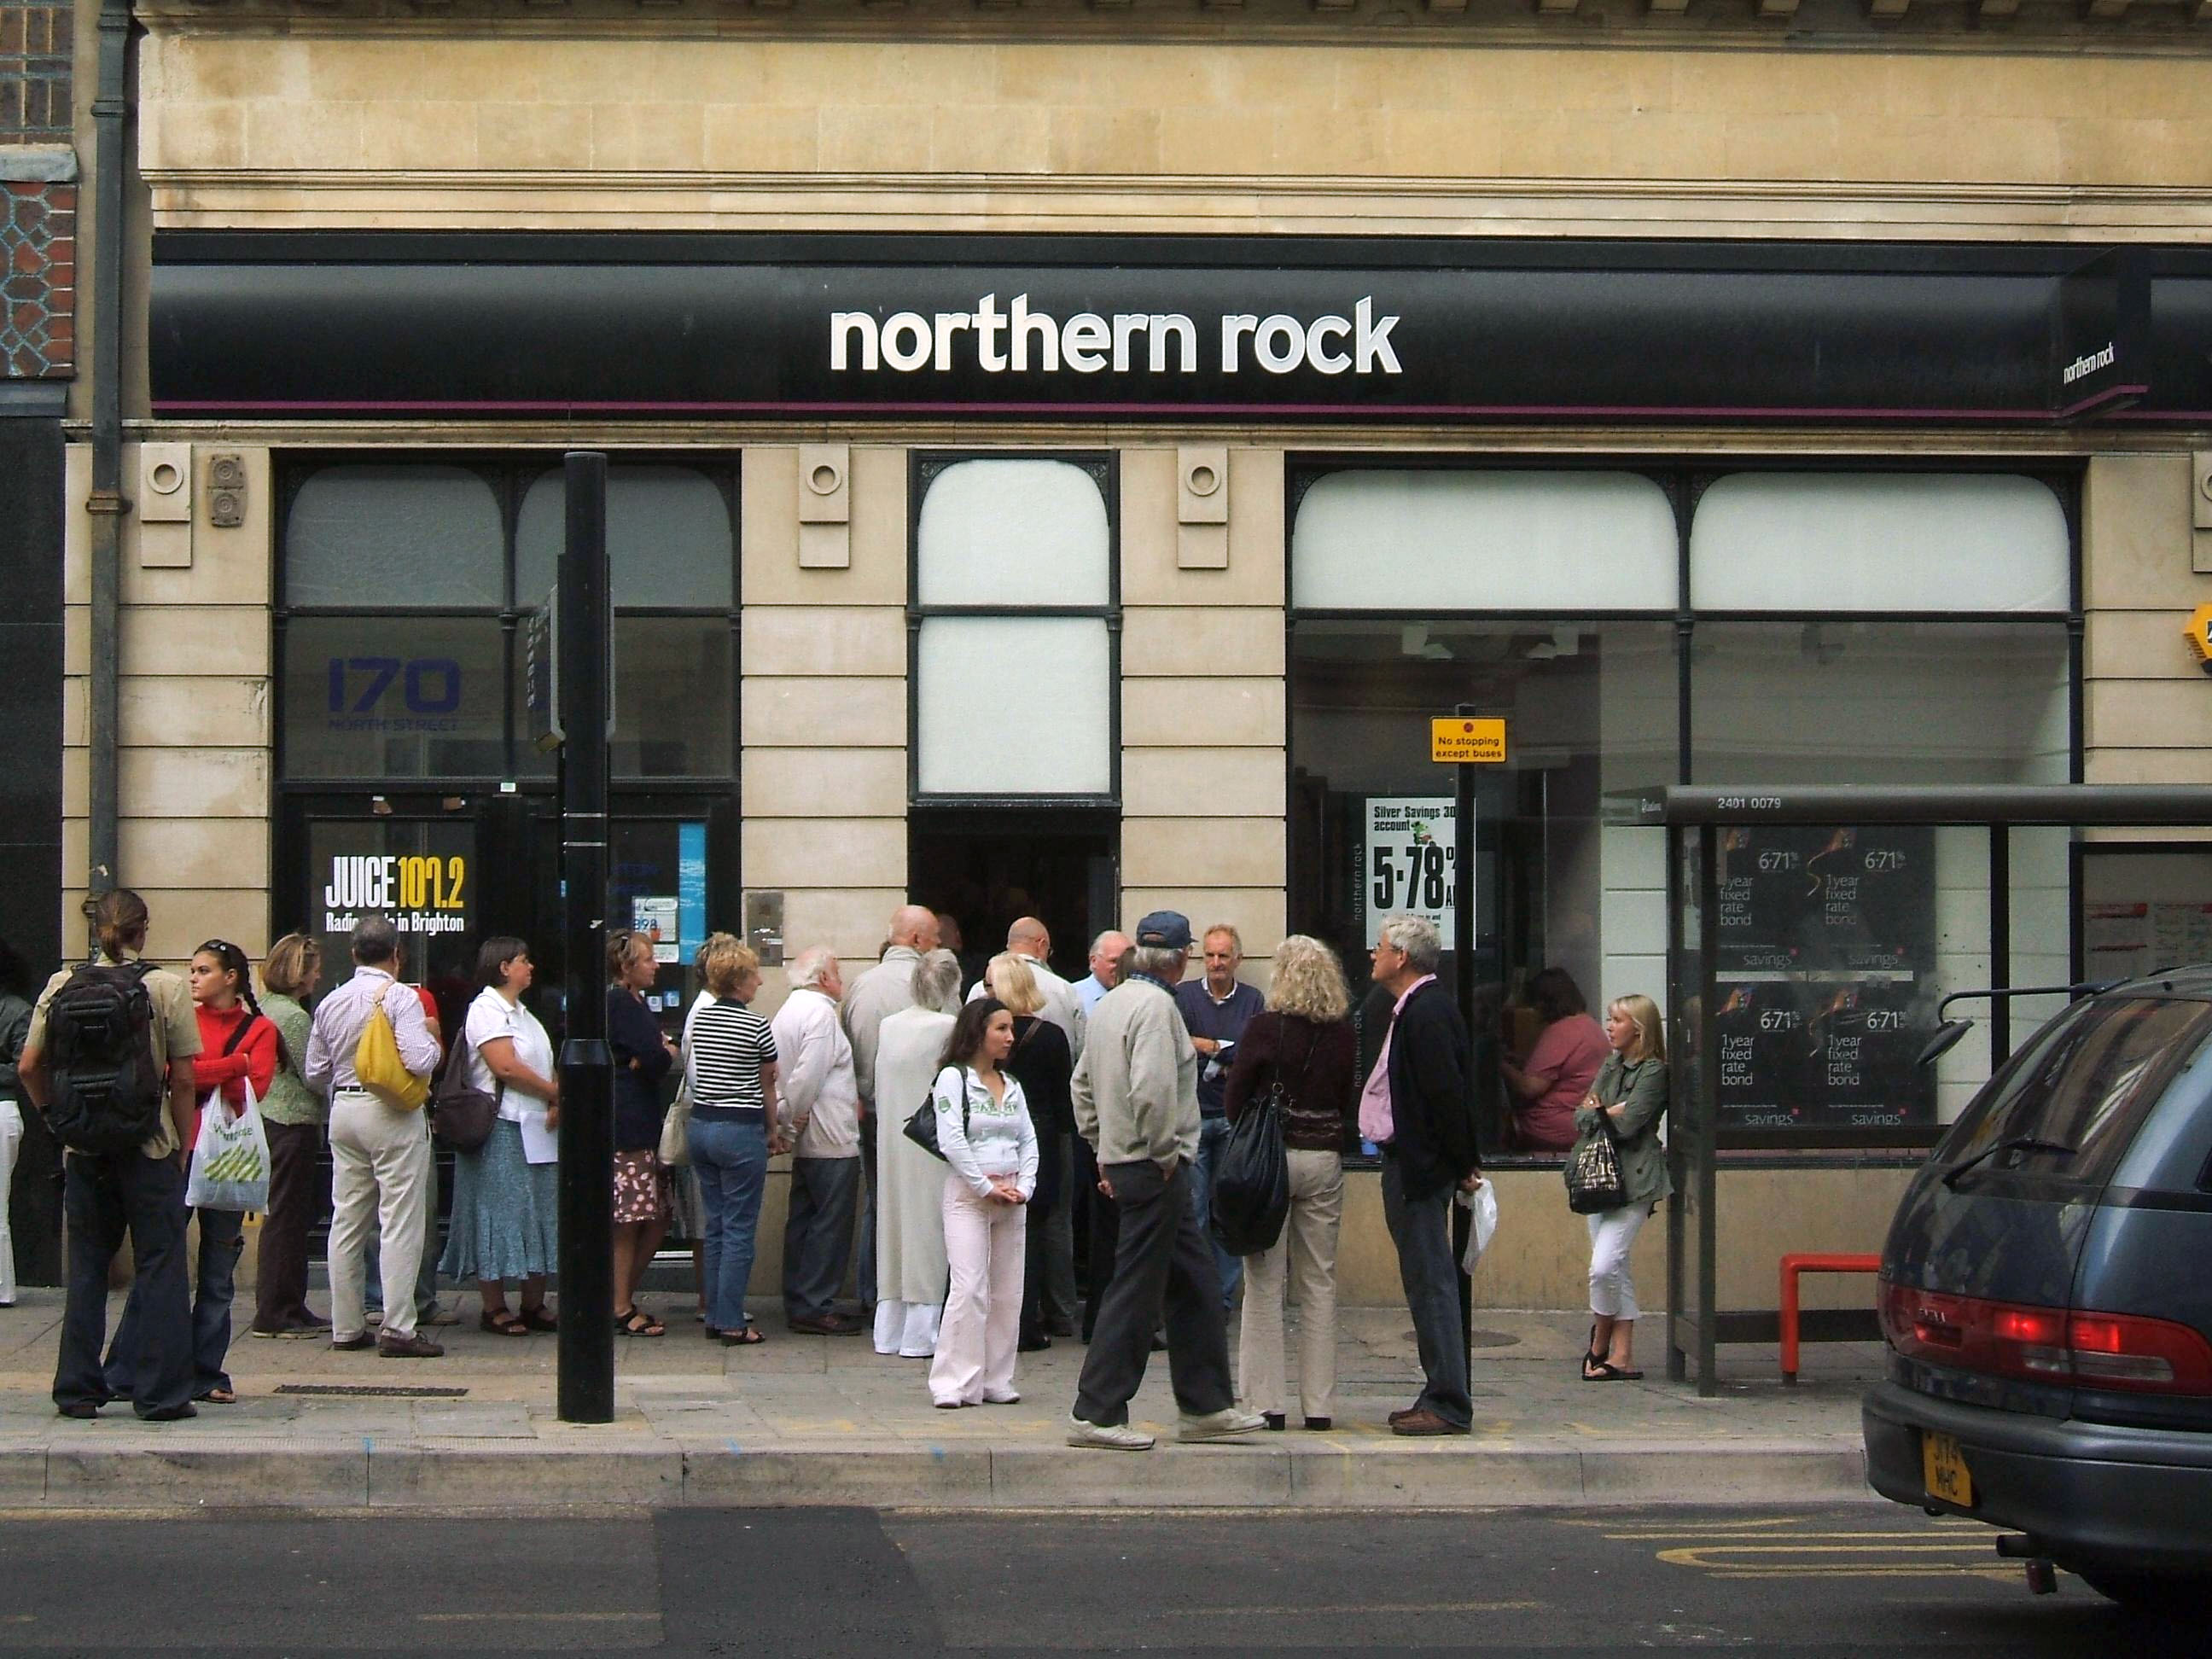](https://upload.wikimedia.org/wikipedia/commons/b/b4/Northern_Rock_Queue.jpg)
*Visual representation of a bank run during the 2008 financial crisis.*
**Practical Applications and Case Studies**
_Case Study 1: The IndyMac Bank Collapse_
IndyMac Bank was a large savings and loan association based in Pasadena, California. In 2008, it suffered substantial losses due to its subprime mortgage business in the wake of the housing market collapse. The FDIC seized IndyMac Bank in July 2008, making it the fourth largest bank failure in U.S. history at the time. However, FDIC-insured depositors did not lose their savings, as they were fully protected for up to $100,000 (increased to $250,000 in 2010) per depositor per bank (FDIC, 2019a).
_Case Study 2: Washington Mutual Bank's Collapse_
Washington Mutual Bank (WaMu) was a banking subsidiary of Washington Mutual Inc., headquartered in Seattle, Washington. It was the largest savings and loan association in the United States until its bankruptcy in 2008. With $307 billion in assets as of September 2008, WaMu became the largest bank failure in the history of the U.S. (FDIC, 2019b).
[](https://www.pasadenastarnews.com/wp-content/uploads/2023/03/PAS-L-BANKS-0315-1-1.jpg?w=556)
*IndyMac Bank collapse: A case study.*
The FDIC, as the receiver for WaMu, sold the bank's banking operations to JPMorgan Chase & Co. on September 25, 2008. Subsequently, the FDIC used its insurance fund to pay depositors, including those who held more than the FDIC-insured limit. The FDIC, as the acquiring bank for WaMu, had protection from any WaMu obligations, transactions, or activities (FDIC, 2019b).
[](https://cdn.geekwire.com/wp-content/uploads/2023/03/bigstock-Washington-Mutual-Bank-3780171-630x419.jpg)
*Washington Mutual Bank: The largest bank failure in U.S. history.*
**Summerizing Key Insights and Suggestions for Further Exploration**
- Federal deposit insurance serves as a safety net that upholds public trust in the banking sector, protects depositors, and mitigates systemic risk during financial crises.
- A properly functioning deposit insurance system, such as the one offered by the FDIC, plays a crucial role in reducing the impact of bank failures and helps maintain financial stability.
- For further study, college students can explore the development of federal deposit insurance across various countries and the effectiveness of different insurance schemes in maintaining financial stability. Additionally, a comparative analysis of different deposit insurance schemes might shed light on the optimal design and structure of deposit insurance.
_References_
- Bernanke, Ben S., Timothy F. Geithner, and Henry M. Paulson Jr. *Firefighting: The Financial Crisis and Its Lessons.* Penguin, 2019.
- Federal Deposit Insurance Corporation (FDIC). "IndyMac Bank, F.S.B." Accessed February 25, 2023. .
- Federal Deposit Insurance Corporation (FDIC). "Washington Mutual Bank." Accessed February 25, 2023. .
- The White House. "President Bush Announces Additional Measures to Strengthen Financial Markets." Press Release, September 29, 2008. Accessed February 25, 2023. .
Last updated: 2024-04-13
Related Books
Related Knowledges